Your 401(k) has a second account. Almost nobody opens it.
About one in four employer plans includes a self-directed brokerage window — Schwab's PCRA, Fidelity's BrokerageLink. It turns the 15-fund menu into the whole market, inside the same 401(k). We read the public filings to find the plans that have it. Yours may be one.
The only public search of 401(k) filings for this benefit that we know of.
What it is
Inside roughly one in four employer 401(k)s there's a second account most people never see. Schwab calls it the Personal Choice Retirement Account. Fidelity calls it BrokerageLink. Your plan documents call it a self-directed brokerage window. Whatever the name, it does one thing: it takes your 401(k) from the 15 or 20 funds your employer picked to the whole market — individual stocks, ETFs, thousands of funds, gold — without the money ever leaving the plan or losing its tax treatment.
15–20 funds your employer picked
stocks, ETFs, funds, gold — same 401(k)
It isn't a loophole. It's a plan feature your employer chose to include, reported every year on a public filing. Schwab's own description says it's for people who take an active role in their retirement savings or who work with an advisor. Which is why the people who have it rarely use it: nobody told them, and nobody at work is allowed to advise them.
How we know your plan has it
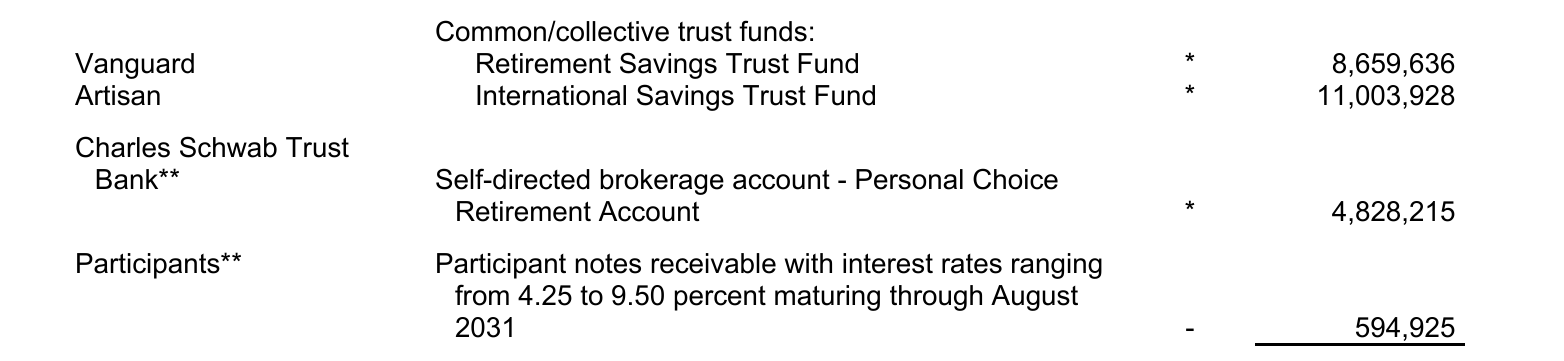
Every 401(k) files an annual report with the U.S. Department of Labor. When the plan includes a brokerage window, the report says so, and the audited financial statements usually name the provider. We read those filings — more than 30,000 of them — so you don't have to. Here is the line from one Utah employer's 2024 audit:
Three ways to use it. You pick how far you go.
- Do it yourselfWe show you your plan's filing, what the window allows, what it costs, and exactly how to turn it on. No advisor, no fee, no one calls you.
- Get a professional opinionAsk us and we'll introduce you to a licensed fiduciary advisor who works inside 401(k) brokerage windows. A free first conversation; you decide what happens next. No one pays us for the introduction.
- Have it managedIf you'd rather it were handled, the advisors we introduce can manage the window for a fee, deducted from the account, never a bill. Fiduciary means legally required to act in your interest.
Most people start in the middle.
Why you haven't heard of it
Your employer can't legally give you investment advice. So they mention the core fund menu and stop there. The window is in the plan documents. Nobody walks you to it.
90-second explainer
Questions people ask
Is this legit?
The account is a real feature of your own plan, run by your plan's recordkeeper. We don't hold your money and never ask for passwords. Everything we tell you about your plan comes from its public Department of Labor filing, and we show you the page.
What does it cost?
Checking your plan is free. Opening the window is usually free from Schwab; some plans charge a small administrative fee, typically $25 to $100 a year, set by the plan. Listed stocks and ETFs trade commission-free; thousands of mutual funds have no transaction fee. Check your plan's fee disclosure for yours.
Will you tell me what to invest in?
No. SDBA Unlock explains the option, shows you your plan's filing, and walks you through turning it on. We don't give investment advice. If you want advice, ask and we'll introduce you to a licensed fiduciary advisor.
I already have an advisor.
Ask whether they can work inside your 401(k). Many don't, because they never see that account. If they can, you're set. If not, the window is where the rest of the market lives.
I'm close to retirement.
You can usually keep using the plan after you retire, window included. Worth knowing before you roll anything anywhere.
What's it called in my plan?
Log into your 401(k) portal and look for "brokerage," "self-directed," "PCRA," or "BrokerageLink." It's usually under investment options, sometimes a level down. Or check here and we'll tell you what the filing says.